
Last updated October 17, 2026
 Metal roofing
 Architectural shingles
 Tile roofing
 GAF
 Owens Corning
 Flat & low-slope
Free roof inspection with deck photos before we talk money - GAF and Owens Corning certified installation
Roofing Cost Breakdown: The Fort Lauderdale Homeowner’s Reference for 2026
The cheapest roofing quote you’ll get in Fort Lauderdale is almost always missing one of three things: the correct underlayment spec for HVHZ, the permit fee, or the post-installation documentation your insurance carrier will ask for at your next renewal. That’s not a guess; it’s a pattern we’ve watched play out across thousands of roofs in this city. This guide walks you through what a Fort Lauderdale roof actually costs in 2026, line by line, so you can spot the difference between a fair quote and a lowball that will cost you more in the long run. For more guides & resources, see our blog.
Styles & brands we work with
Quick Answer
A full roof replacement on a typical Fort Lauderdale home runs $14,000 to $28,000 in 2026, with most single-story homes landing between $16,000 and $22,000. Roof repairs run $450 to $1,800 for most jobs. Fort Lauderdale roofing costs run 15-25% above national averages because of HVHZ code compliance, impact-rated material requirements, and the insurance documentation labor that responsible contractors build into their pricing.
Table of Contents
- Why Fort Lauderdale Roofs Cost More: The 15-25% Premium Explained
- Line-Item Cost Breakdown: What a 2026 Re-Roof Actually Includes
- Impact-Rated Shingles: The Upfront Cost That Pays You Back
- The Hidden Costs That Turn a $12,000 Estimate Into a $16,000 Invoice
- How to Read a Written Roofing Estimate Line by Line
- Financing and Insurance Claim Coordination: What Responsible Contractors Do Differently
- Common Mistakes to Avoid
- When to Call a Professional
- Frequently Asked Questions
- The Bottom Line
Why Fort Lauderdale Roofs Cost More: The 15-25% Premium Explained
Roofing costs in Fort Lauderdale are not inflated by greed. They’re inflated by geography, code, and weather. If you’ve compared a quote from a roofer in Fort Lauderdale against a national average you found online, you’ve probably noticed the gap. Here’s what’s actually driving it.
First, Fort Lauderdale sits inside the High Velocity Hurricane Zone, or HVHZ, a code designation that covers Broward and Miami-Dade counties. This isn’t a suggestion; it’s law. HVHZ requirements govern everything from the type of underlayment you can install to how many nails go in each shingle to the specific way roof decking gets fastened to trusses. A roofer working in Fort Lauderdale has to buy different materials and spend more time on installation than a roofer working in Orlando or Tampa, where the standard Florida Building Code applies without the HVHZ addendum.
Second, impact-rated materials cost more. The shingles themselves, the underlayment, the sealants, the fasteners, all of it. A Class 4 impact-rated shingle from Owens Corning or Atlas runs 25-40% more per square than a standard architectural shingle. In Fort Lauderdale, that upgrade is frequently not optional, it’s the minimum required for insurance discounts that many homeowners rely on to keep their premiums manageable.
Third, there’s the insurance documentation labor. A responsible Fort Lauderdale roofing contractor photographs the tear-off, documents the deck condition, files the permit closure with the city, and provides the paperwork your insurance carrier needs at renewal time. That labor takes hours and it’s built into the price. Contractors who skip it can quote lower. Those are also the contractors whose work you’ll be fighting to prove when your carrier asks for evidence of a compliant install two years later.
We’ve also seen the premium show up in disposal and logistics. Fort Lauderdale’s tighter job sites, HOA rules in neighborhoods like Victoria Park and Rio Vista, and city disposal fees all add cost. So does the heat. Roofing crews in Fort Lauderdale work shorter shifts in summer months, which extends labor timelines slightly and shows up in the final number.
Line-Item Cost Breakdown: What a 2026 Re-Roof Actually Includes
A legitimate Fort Lauderdale roofing estimate separates costs by line item. If your quote is one number with no breakdown, that’s a red flag. Here’s what you should see on a full re-roof for a standard 1,800 to 2,200 square foot single-story home in Fort Lauderdale in 2026.
| Line Item | Typical 2026 Range | What It Covers |
|---|---|---|
| Materials (shingles, underlayment, fasteners, flashing) | $7,500 – $12,500 | Impact-rated shingles, HVHZ-compliant underlayment, drip edge, pipe boots, ridge vent |
| Labor (tear-off and installation) | $5,500 – $8,500 | Crew time for removal of old roof, deck prep, and new roof installation |
| Permit and inspections | $600 – $1,200 | City of Fort Lauderdale permit fee, HVHZ inspection scheduling, final sign-off |
| Disposal, dump fees, and site protection | $800 – $1,500 | Dumpster rental, landfill fees, ground cover, magnet sweeping for nails |
| HVHZ compliance premium | $1,500 – $3,000 | Additional fasteners, secondary water barrier, code-required details not present in non-HVHZ installs |
| Insurance documentation package | $0 – $400 | Photo documentation, permit closure filing, wind mitigation documentation where applicable |
These ranges reflect what we see across Fort Lauderdale’s market in 2026 for a standard architectural impact-rated shingle roof. Tile roofs run higher, often $25,000 to $45,000 depending on tile type and whether the existing tile can be reused. Flat or low-slope roofs with modified bitumen or TPO membranes fall between $18,000 and $30,000 for typical Fort Lauderdale homes.
One thing worth saying plainly: the HVHZ compliance premium is not a made-up fee. It represents materials and labor that a code-compliant roofer cannot skip. If a quote doesn’t show it as a line item, it means either the roofer folded it into another line or the roofer isn’t doing HVHZ-compliant work. The second possibility is the dangerous one.
For homeowners looking at Roof Replacement in Fort Lauderdale, this breakdown is the baseline for evaluating any estimate you receive.
Impact-Rated Shingles: The Upfront Cost That Pays You Back
Class 4 impact-rated shingles cost more upfront in Fort Lauderdale, typically $1,200 to $2,500 more per roof than standard shingles. But for many homeowners, that premium returns $800 to $1,500 per year in insurance discounts from Citizens Insurance or private carriers.
Here’s how that math works. Citizens Property Insurance, the state-backed insurer of last resort that covers a huge share of Broward County homes, offers significant premium reductions for homes with verified wind mitigation features. A Class 4 impact-rated roof is one of the weightiest line items on a wind mitigation inspection report. Private carriers like State Farm and Universal Property offer similar credits.
Over a 10-year span, a homeowner who saves $1,200 per year on premiums recovers the upfront cost difference between the third and fourth year. After that, the savings stack. And the shingle itself lasts longer in Fort Lauderdale’s weather, because impact-rated shingles resist the hail and wind-driven debris that degrade standard shingles faster in this climate.
Brand matters here too. Owens Corning’s Duration Storm and Atlas StormMaster Shake lines are specifically built for high-wind coastal zones and carry the Class 4 UL 2218 rating. IKO’s Nordic line offers similar impact resistance. These shingles use a polymer-modified asphalt that flexes instead of cracking under impact, which is why they survive the debris strikes that shatter standard shingles during a Fort Lauderdale thunderstorm.
One caution: a Class 4 rating only matters if the roof is installed to the manufacturer’s HVHZ spec. An impact-rated shingle installed with the wrong underlayment or the wrong nail pattern fails the wind mitigation inspection and you lose the insurance discount regardless of what the shingle package says. That’s why we’re particular about installation details, and it’s why the written estimate should specify the exact shingle, the exact underlayment, and the exact fastening schedule being used.
If you’re considering a full Roof Installation in Fort Lauderdale, ask your contractor to show you the wind mitigation form they’ll fill out after the job. A contractor who doesn’t know what that form is won’t get you the insurance discount.
The Hidden Costs That Turn a $12,000 Estimate Into a $16,000 Invoice
The stories we hear most often sound the same: a homeowner gets a low quote, signs it, and then watches the price climb once the roof is torn off. Here are the three most common drivers of that gap in Fort Lauderdale.
- Deck rot discovery. When the shingles come off, the plywood or OSB underneath is sometimes water-damaged and spongy. Code requires replacement. That’s typically $2,500 to $4,500 for partial deck replacement on a standard Fort Lauderdale home. A roofer who doesn’t mention this possibility before starting is either inexperienced or setting you up for a surprise.
- Code-required drip edge replacement. Drip edge, the metal strip that directs water away from the fascia board, is frequently missing or corroded on older Fort Lauderdale homes. HVHZ code requires it. That’s $800 to $1,800 depending on roof perimeter length, and it’s a line item that should be in your original estimate, not added after the fact.
- Permit revision fees. If the city inspector finds an issue that requires plan changes, the city charges for the revision. That’s $150 to $400. More importantly, the delay adds days to your project. A contractor who has done hundreds of Fort Lauderdale roofs knows what inspectors flag and builds that knowledge into their estimate from day one.
There’s also the less obvious cost: re-roofing a home where the deck fastening doesn’t meet current HVHZ nail pattern requirements. Fort Lauderdale homes built before the 2001 adoption of stronger wind codes often have decking nailed down with too few nails, at the wrong spacing. Code requires adding fasteners. That’s labor-intensive and costs $1,000 to $2,500 depending on roof size.
None of these costs are scams. They’re real conditions that exist under shingles you can’t see from the ground. The distinction is whether the contractor warned you about them, before you signed.
How to Read a Written Roofing Estimate Line by Line
A written roofing estimate in Fort Lauderdale should break out at least eight separate categories. Here’s what to look for, and what’s missing when a contractor is hiding something.
- Materials with exact product names. “Architectural shingle” is vague. “Owens Corning Duration Storm Class 4, color: Driftwood” is specific. Specific names let you verify prices and quality.
- Underlayment spec. In Fort Lauderdale, this should state the exact underlayment product and whether it meets HVHZ requirements. If the line just says “felt paper,” that’s a non-compliant shortcut on a Fort Lauderdale roof.
- Fastening schedule. HVHZ code specifies nail count and pattern. The estimate should mention it. If it doesn’t, the contractor may be planning to nail to a non-HVHZ standard.
- Permit line item with city name. It should say Fort Lauderdale permit fee specifically. A contractor who lumps permit costs into “miscellaneous” may not actually pull the permit, which is illegal and voids your insurance claim later.
- Disposal and cleanup detail. This should specify dumpster rental, magnet sweep, and final site walk. If it says “cleanup included” with no detail, expect nails in your driveway.
- Deck replacement clause. The estimate should say what happens if deck rot is found: per-sheet replacement cost, documented and approved before proceeding.
- Insurance documentation. Look for language about final photos, permit closure filing, and wind mitigation paperwork. If it’s absent, the roofer won’t provide the documentation your carrier requires.
- Start date, duration, and payment schedule. No deposit before permits are pulled. No final payment before the city inspection passes. Anything else puts you at risk.
At Crestview Roofing Co Fort Lauderdale, our written price comes before any work starts and the number on the estimate is the number on the final invoice. That’s the whole point of our approach and the reason we put it in writing on every job. If you’re comparing estimates, hold every contractor to the same standard. Ask for the line items. If they won’t provide them, that’s your answer.
Financing and Insurance Claim Coordination: What Responsible Contractors Do Differently
Most Fort Lauderdale homeowners replace a roof for one of two reasons: the roof reached the end of its service life, or wind and storm damage triggered an insurance claim. They require different processes, and the contractor you choose should understand both.
For out-of-pocket replacements, financing is common. Many Fort Lauderdale homeowners use home equity lines, unsecured home improvement loans, or contractor-offered financing. Rates in 2026 range from 6.9% to 15.9% APR depending on credit. Some contractors partner with lenders like GreenSky or Service Finance. Ask about the exact APR, the term length, and whether there’s a prepayment penalty before signing anything.
For insurance claims, the process matters even more. When a storm damages your roof, your carrier sends an adjuster who writes a scope-of-loss document. That document determines whether the carrier pays for a full replacement or a repair-only settlement. Responsible contractors in Fort Lauderdale walk the roof with the adjuster, point out damage the adjuster might miss, and document everything with photos. That documentation is often the difference between a $4,000 repair payout and a $22,000 replacement approval.
Here’s the sequence we recommend to Fort Lauderdale homeowners filing a claim:
- Photograph the damage yourself from the ground immediately after the storm, before anything gets touched.
- Call your insurance carrier and file the claim. Do not sign anything from a door-knocking contractor before this step.
- Get a licensed roofing contractor to inspect and document the damage in writing.
- Have your contractor present when the adjuster arrives, sharing their photos and findings.
- Review the adjuster’s scope-of-loss against your contractor’s written estimate line by line.
- If the carrier’s settlement looks low, ask your contractor to submit a supplement, a formal request for additional payment based on documented conditions the adjuster missed.
Supplementing is a normal, legitimate part of the insurance process in Fort Lauderdale. A good roofer does it routinely. A roofer who never supplements is either leaving money on the table for you or not documenting their work in the first place.
If you need repairs rather than a full replacement, our Roof Repair in Fort Lauderdale process follows the same standard: written price before work starts, photos before and after, and a digital invoice sent by text.
Common Mistakes to Avoid
- Accepting a quote that’s 30% below everyone else. In Fort Lauderdale’s roofing market, a quote that low is missing something: underlayment spec, permit fees, insurance documentation, or all three. The number comes back up after the tear-off.
- Skipping the permit to “save money.” An unpermitted roof in Fort Lauderdale voids your insurance coverage and creates a legal problem when you sell. The city’s building department flags unpermitted work, and buyers’ inspectors find it.
- Choosing a contractor who won’t walk the roof before quoting. A roofer who quotes from the ground cannot see deck condition, flashing condition, or ventilation problems. The quote is a guess.
- Ignoring the wind mitigation form. In Fort Lauderdale, that single form can be worth more than $1,000 per year in insurance savings. If your roofer doesn’t know what a wind mitigation inspection is, choose another roofer.
- Paying the full amount upfront. Reputable Fort Lauderdale roofers take a deposit at permit pull, a progress payment at material delivery, and final payment after the city inspection passes. Full payment before work starts is a red flag.
- Not asking about the 365-day repair guarantee. Most roofing warranties in Fort Lauderdale are manufacturer-backed but installer-dependent. If the contractor won’t put the workmanship guarantee in writing, you have no recourse when the work fails.
When to Call a Professional
Call a professional Fort Lauderdale roofer when you see water stains on ceilings, granule loss in gutters, missing or lifted shingles, daylight through attic decking, or any sign of wind-driven rain intrusion after a storm. Also call before you buy a home: a pre-purchase roof inspection costs less than $250 and can reveal a $20,000 replacement hiding under a fresh coat of paint. If your roof is past 15 years old and you haven’t had an inspection in two years, schedule one. Crestview Roofing Co Fort Lauderdale offers free estimates in Fort Lauderdale. Call (754) 354-8628 to schedule yours.
Frequently Asked Questions
A full roof replacement in Fort Lauderdale runs $14,000 to $28,000 for most homes in 2026, with single-story homes typically landing between $16,000 and $22,000. Tile roofs run higher. Call (754) 354-8628 for an exact written quote, estimates are free.
You need impact-rated shingles if you want the insurance discounts they unlock, which run $800 to $1,500 per year for most Fort Lauderdale homeowners with Citizens or private carrier policies. The shingles cost $1,200 to $2,500 more upfront, so the upgrade pays for itself in two to three years, and the shingles also last longer in coastal weather.
HVHZ stands for High Velocity Hurricane Zone, a stricter building code standard that applies to Broward and Miami-Dade counties including Fort Lauderdale. It requires stronger underlayment, more fasteners, and specific installation details that add 15-25% to the cost of a roof compared to non-HVHZ Florida codes. Call (754) 354-8628 to see how HVHZ applies to your specific roof.
It shouldn’t, if the roofer did a proper inspection and wrote a detailed estimate before you signed. The only legitimate exception is deck rot discovered after tear-off, which no one can see from above. A written estimate should state the per-sheet deck replacement price before work begins, and the roofer should get your approval before proceeding. Ask Crestview Roofing Co Fort Lauderdale about written pricing, call (754) 354-8628 for a free estimate.
A standard shingle roof replacement in Fort Lauderdale takes two to five days for most homes, depending on roof size, pitch, and weather. Tile roofs take longer, often one to two weeks. The city inspection adds a day or two on either end. For a specific timeline on your roof, call (754) 354-8628 and we’ll walk you through it.
Yes, Fort Lauderdale requires a building permit for roof replacement and most full re-roofs, and the work must pass a city inspection. An unpermitted roof voids your insurance coverage and creates problems at resale. Any roofer who suggests skipping the permit is asking you to break the law, call (754) 354-8628 to work with a roofer who pulls permits on every job.
The Bottom Line
Your Fort Lauderdale roof costs more than the national average because it’s built to survive hurricanes, and that’s not a place to save money. Get a written, line-item estimate. Confirm the underlayment meets HVHZ spec. Ask about the permit, the disposal plan, the deck replacement clause, and the wind mitigation paperwork. If a contractor can’t answer those questions in writing, walk away. The roof you pay for today determines what your insurance carrier pays for tomorrow. For a written, no-surprises estimate, call Crestview Roofing Co Fort Lauderdale at (754) 354-8628.
Written by Dylan Pace, Owner at Crestview Roofing Co Fort Lauderdale, serving Fort Lauderdale since 2000.
See the difference
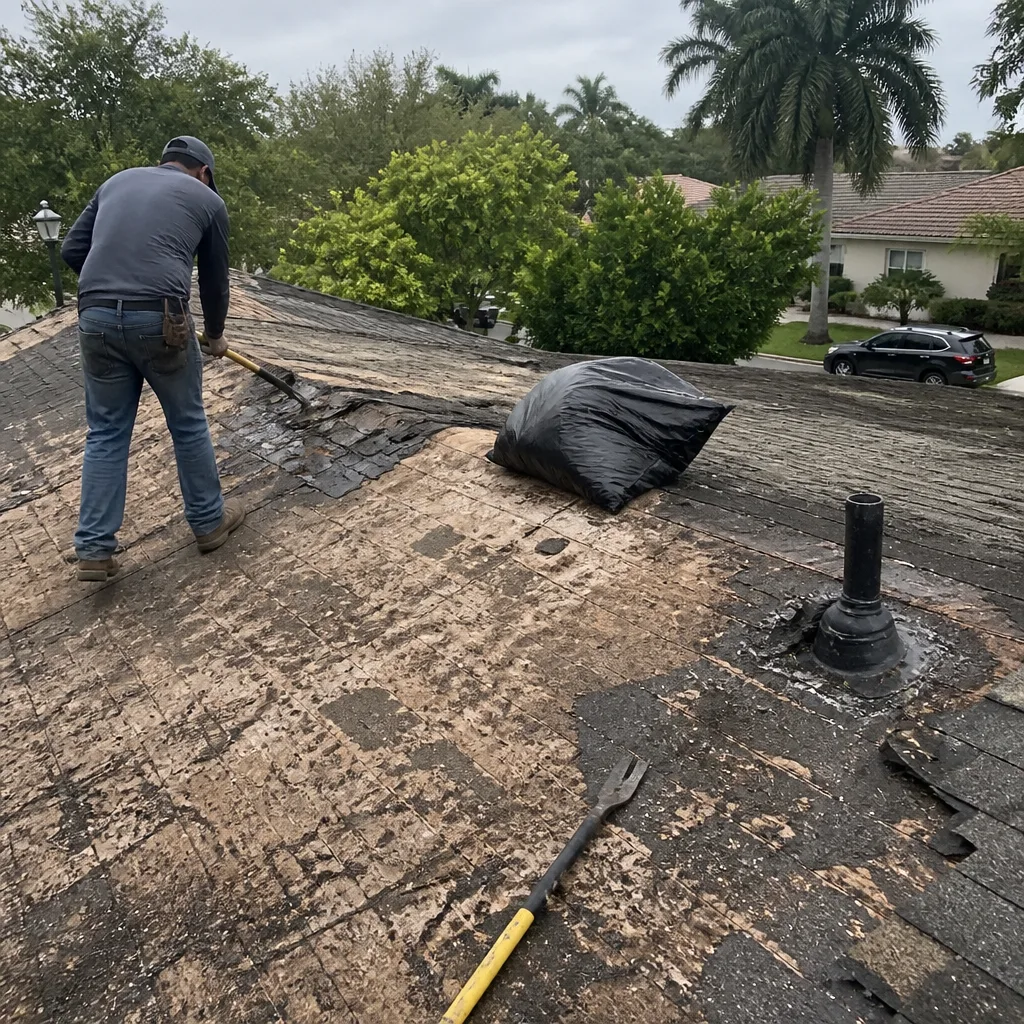 Before
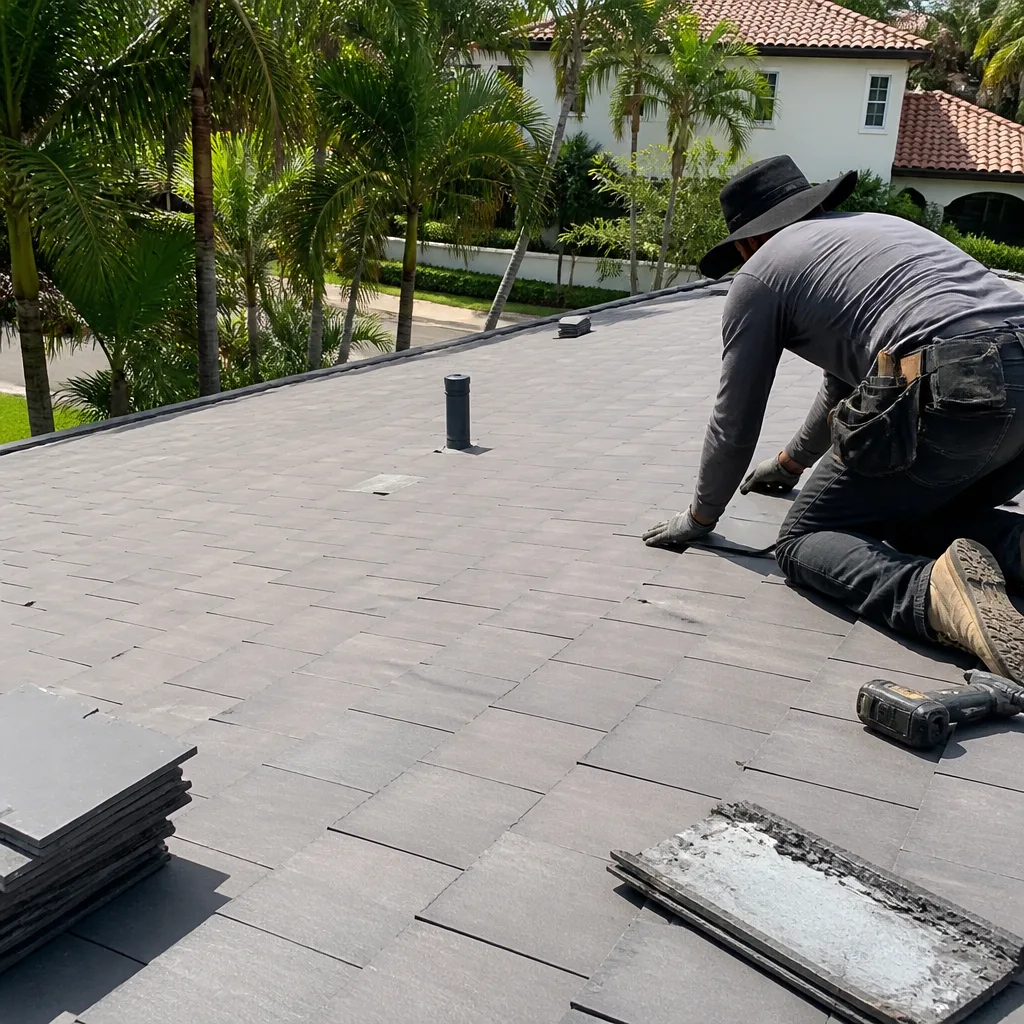 After
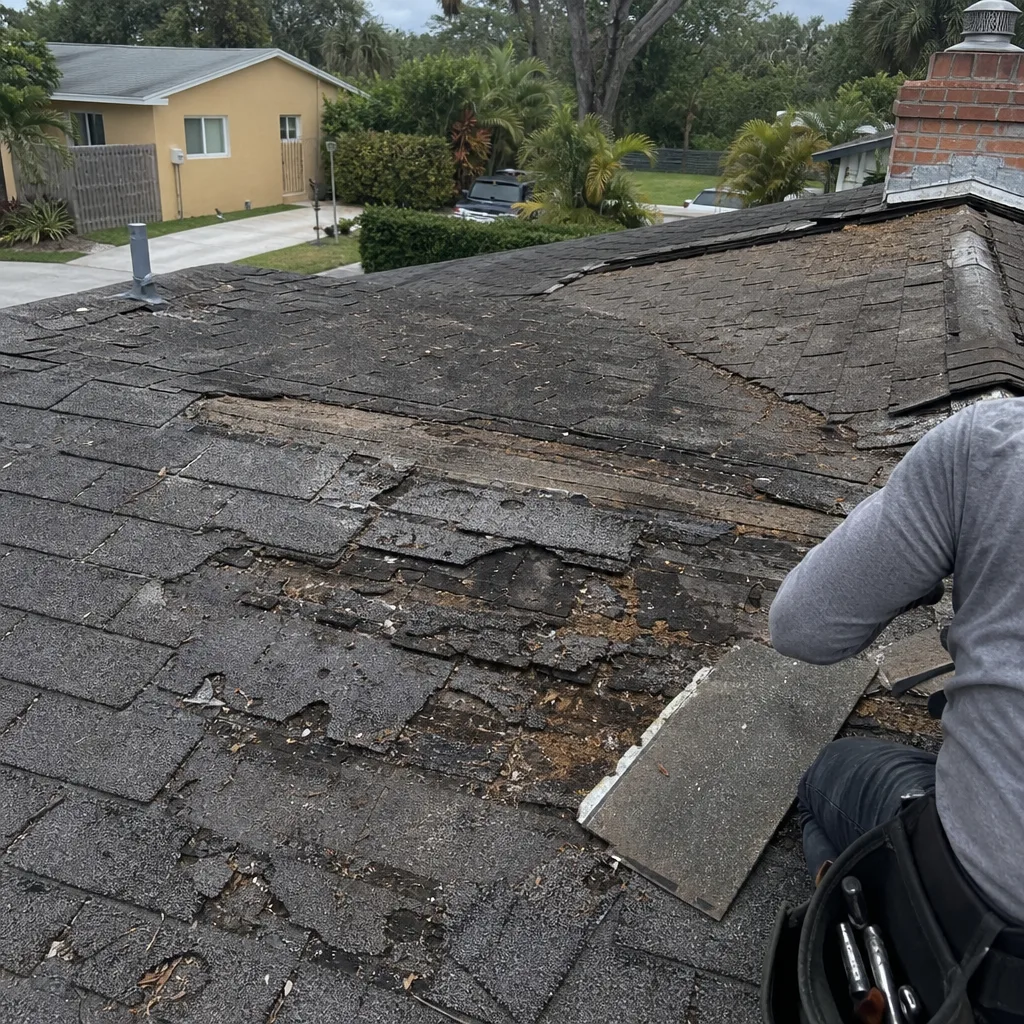 Before
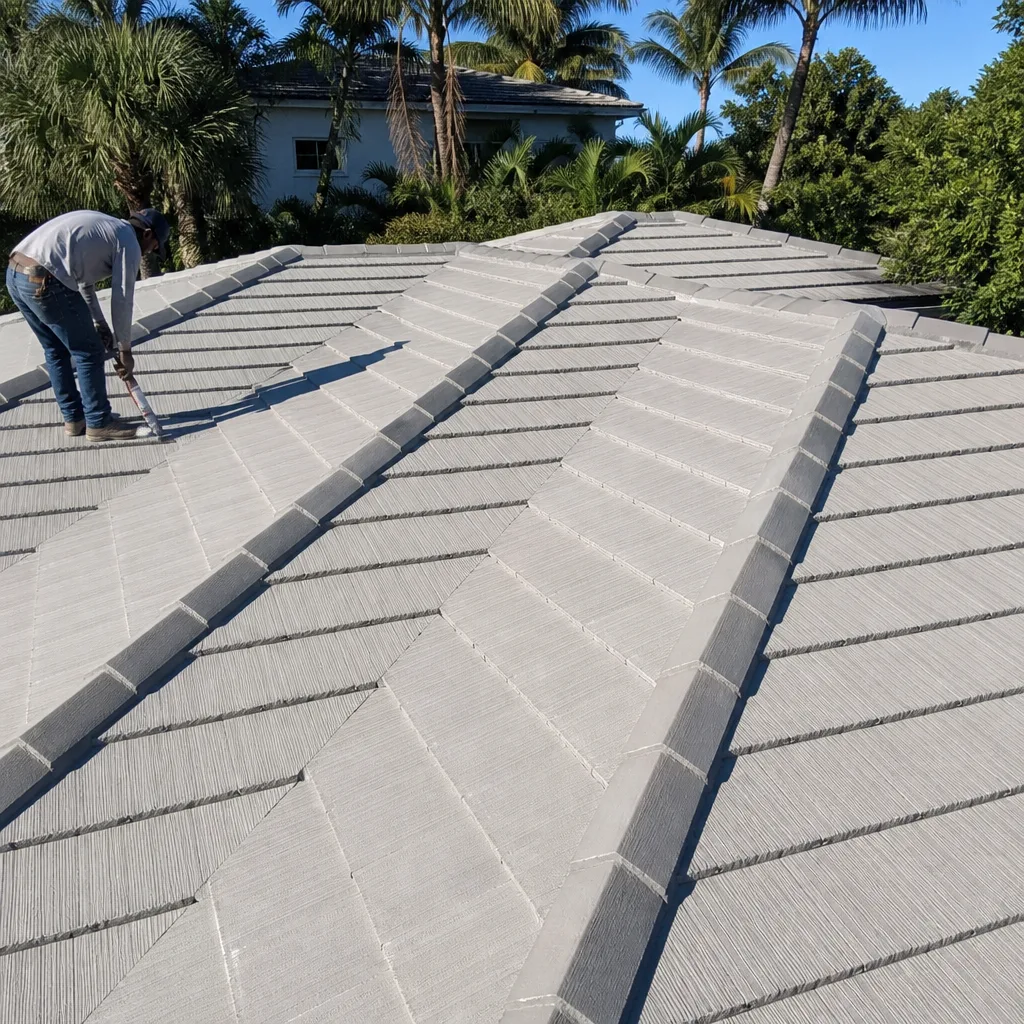 After
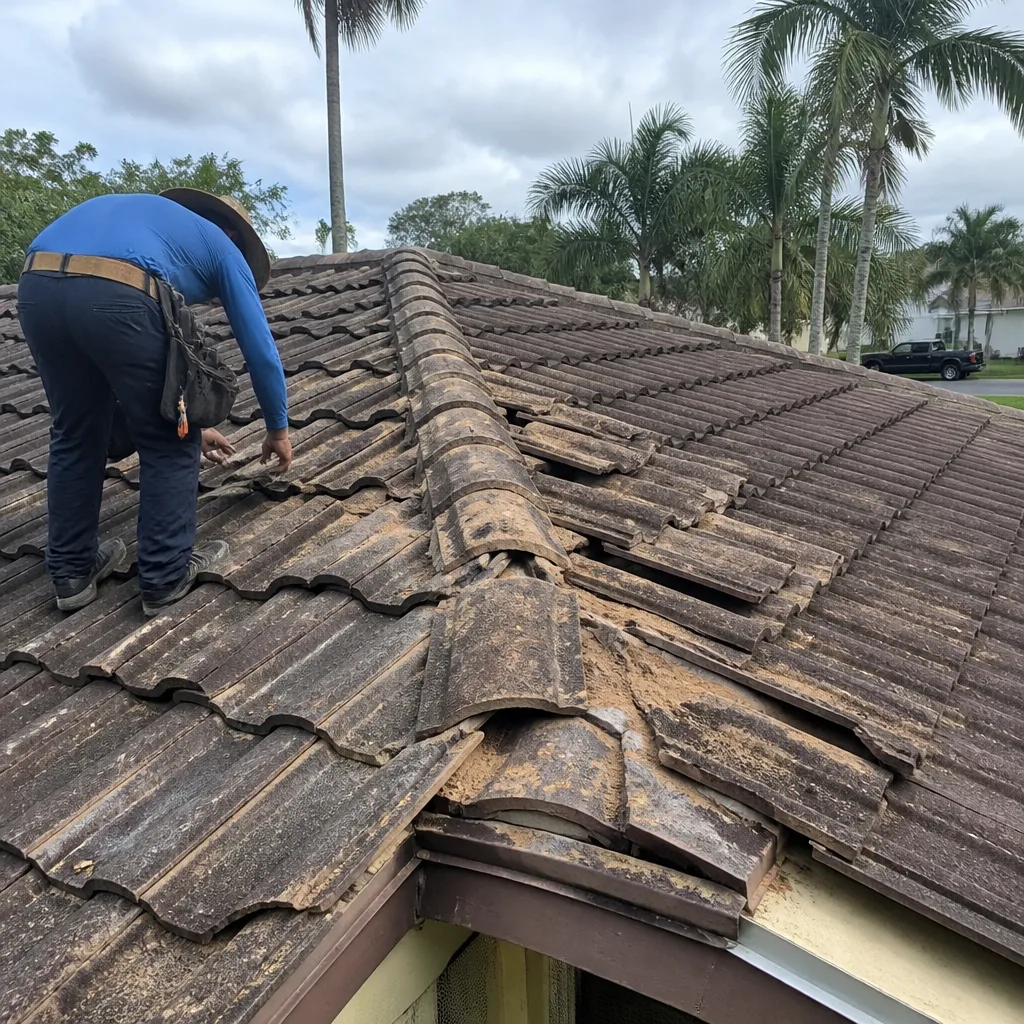 Before
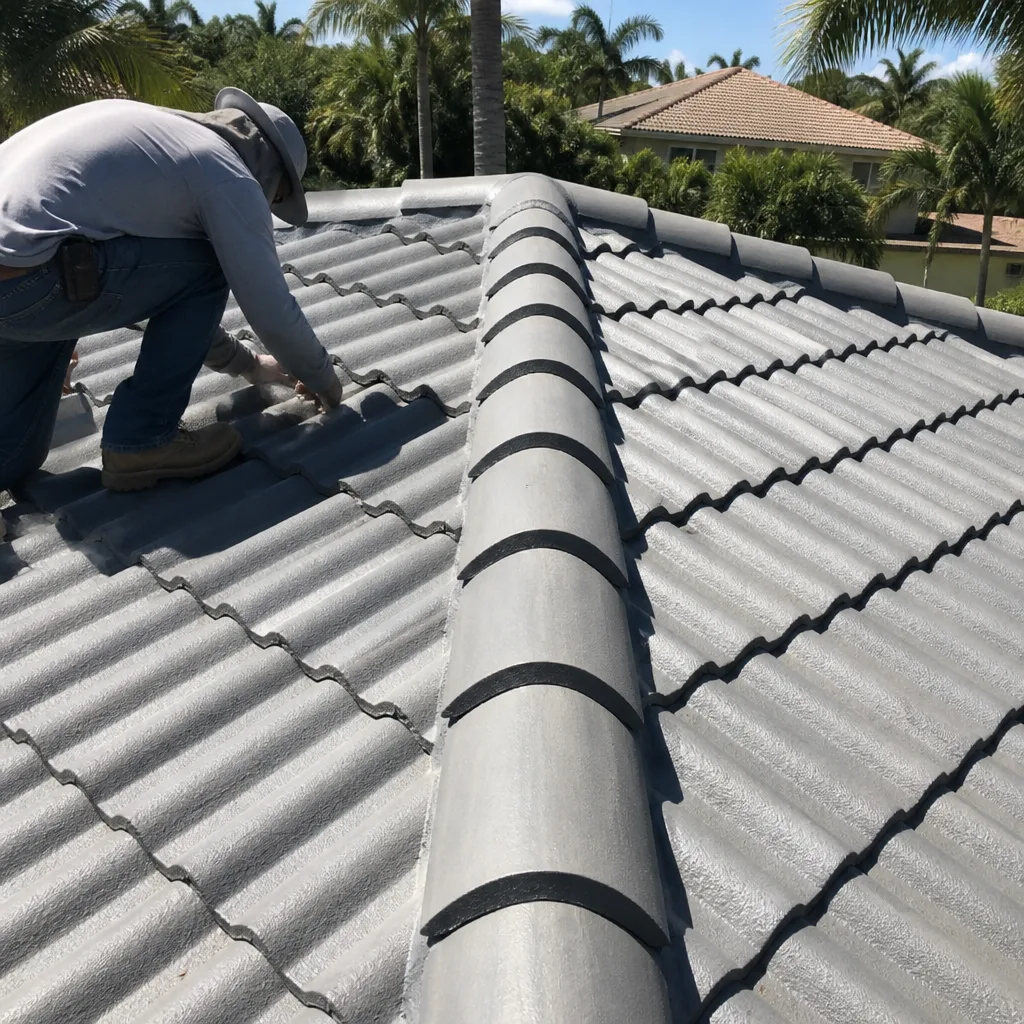 After